
 In the history of artificial intelligence, the term “AI winter” refers to the repeating cycle of hype and disappointment. The term originates from 1984, by which time there had already been several hype cycles.
Wikipedia lists many previous winters. The periods from 1974 to 1980 when DARPA radically cut back academic AI research, and from 1987 to 2000 following the collapse of the LISP machine market are both cited as extended winters. After that we had several hype cycles and busts. For example, in the 90s Japan attempted an ambitious “fifth generation computer” project that ultimately failed, while in the same period in the US there was a fad for “expert systems” that would have human-like domain knowledge.
Now we are in 2026, in the middle of a boom that began around 2020. This hype cycle dwarfs previous cycles, with massive private sector spending. But is this really the final nirvana, or just another boom that will inevitably be followed by an AI winter?
In previous cycles, the barometer of success was how far the technical needle was moved. Now, because of the vast sums that have been spent by venture capitalists, the barometer can be nothing less than massive financial returns. In other words, AI has to truly deliver earth-changing results, or else we’ll fall into an AI winter because its fate is tied to how much money it generates.
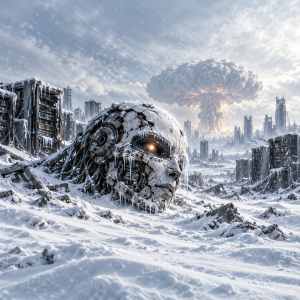
Perhaps, given the scale, just just a winter, but the mother of all AI winters: an AI nuclear winter. If this term catches on, remember you heard it here first.
According to Apollo economist Torsten Slok, we may be headed that way. In a piece published this past weekend, he notes that so far, AI has not resulted in any payoff whatsoever:
Despite massive investments and widespread hype around artificial intelligence, the technology has delivered zero financial payoff to corporate America outside of tech. Revenue per worker is rising for the Mag 7 but is flat for the S&P 493, see the first chart below. Profit margins are rising for the Mag 7 but are flat for the S&P 493, see the second chart below. And there are still no signs of AI boosting productivity growth, see the third chart below. With no impact on the bottom line, mainstream corporate America is pulling back and starting to view token spending not as a source of growth but as a cost center that weighs on margins.
His charts show how revenue per employee and profit margins are going up for the tech sector – the people selling AI mostly – but there is not a similar translation for tech’s customers. The Magnificent Seven are cashing in, but not the other 493 companies in the S&P 500.
Huh? Shouldn’t AI be lifting all boats? If the technology can really replace humans with cost-efficient machines, shouldn’t we be starting to see that? Lord knows, there are a lot of wannabe gurus predicting that.
Just follow that trendline, even without a chart or calculations. If AI isn’t delivering any ROI, then non-tech companies like Coca-Cola, Dow, and Exxon are not going to spend money on it. Hence, there will be no giant economic return for the companies funding AI, hence…
AI nuclear winter. I’m quite proud of that term.
Related Posts:
About Those Microsoft Early Buyouts...
Large-Scale Thefts of AI GPUs are Surging and the Crimes are Increasingly Sophisticated
Anthropic's IPO is Coming Soon. Should You Buy? Here are the Four Most Important Things to Think Abo...
My Books Were Used to Train AI. How Should I Feel About That?
PortableMind: The Offline AI on a USB You Can Run on Your Laptop - Privacy, Survival Info, and More!
How to Get Sued Into Oblivion: Guardian Angel AI

raindog308 is a longtime community LETizen, technical writer, and self-described techno polymath. With deep roots in the *nix world, he has a passion for systems both modern and vintage, ranging from Unix, Perl, Python, and Golang to shell scripting and mainframe-era operating systems like MVS. He’s equally comfortable with relational database systems, having spent years working with Oracle, PostgreSQL, and MySQL.
As an avid user of LowEndBox providers, raindog308 runs an empire of LEBs, from tiny boxes for VPNs, to mid-sized instances for application hosting, and heavyweight servers for data storage and complex databases. He brings both technical rigor and real-world experience to every piece he writes.
Beyond the command line, raindog308 has a life-long love of German Shepherd Dogs, high-quality knives, target shooting, theology, tabletop RPGs, playing guitar, and hiking in deep, quiet forests.
His goal with every article is to help users, from beginners to seasoned sysadmins, get more value, performance, and enjoyment out of their infrastructure.
You can find him daily in the forums at LowEndTalk under the handle @raindog308.
Leave a Reply